Following Fed Chairman Kevin Warsh’s hawkish speech at the Jackson Hole symposium in August, interest rates have risen across the curve. On September 11, 2026, the U.S. 2-year note yield briefly reached the highest since July 2024 (over 4.60%), and similarly the US 10-year yield touched on its highest level since November 2023 (almost 4.97%)1.
There are good reasons for upward pressure on interest rates, including strong U.S. labour data in August 2026; inflation persistently above the Fed’s 2% target for more than 5 years; and rising energy costs, with crude oil now above US$100/barrel. There are no easy fixes to these drivers of higher interest rates, and they are pointing to potential near-term Fed Funds rate hikes.
A recent Reuters poll of economists conducted September 4-9, 2026 indicated that 54% believed there would be no Fed hike in September, down from 77% calling for no change in the August poll2. Adding to rate-hike pressure, on September 11 the Department of Labour announced US CPI for August 2026 increased year-over-year (to 3.4%), and the Fed Funds Futures markets began pricing in > 80% chance of a rate hike at the September 15–16 Fed meeting3. Whatever happens at the Fed meeting, interest rate risk is back, and it’s growing more intense.
CLO Performance vs Fed Fund Rate Hikes, 2022/2023
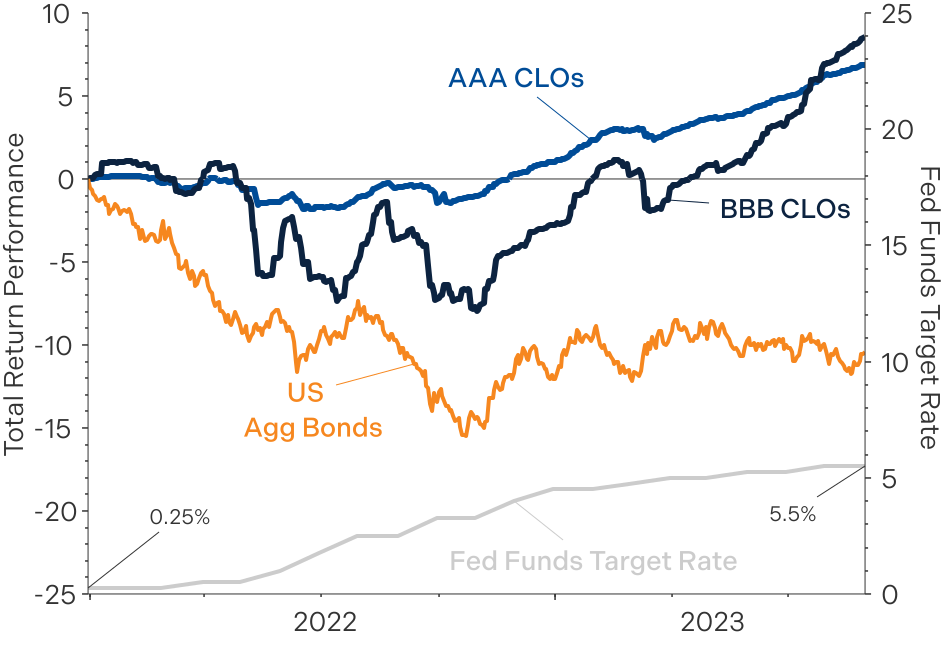
Source: LSEG Datastream, data from 31/12/2021 - 31/08/2023
During the 2022/2023 interest rate hike cycle, the U.S. bond market broadly underperformed, with few exceptions. Investment Grade CLOs were one of the better performing asset classes during that volatile period4. Importantly, investors who re-allocated to CLOs before actual Fed Fund rate hikes began, did well relative to the broader fixed income market during this period, as the longer part of the interest rate curve started to rise in advance of actual Fed Fund hikes (much as the interest rate curve is doing now).
Investment grade CLOs offer:
- Minimal duration risk – Very little sensitivity to rising bond yields due to renewed inflation pressures, unlike the broader fixed income market.
- Attractive income – Risk-adjusted yields for CLOs are among the highest in the fixed income market. CLO’s floating-rate coupons adjust higher with rising short-term rates.
- High credit quality – Highest-quality AAA CLOs have experienced zero defaults, and other Investment Grade-rated CLO tranches have a minimal default history when compared to similarly-rated corporate bonds.
Brompton Wellington Square AAA CLO ETF (TSX: BAAA ,BAAA.U) provides investors with attractive monthly income through an actively managed portfolio focused primarily on AAA-rated CLOs. Brompton Wellington Square Investment Grade CLO ETF (TSX:BBBB, BBBB.U) aims to deliver high floating-rate monthly income by investing predominantly in investment-grade CLO bonds.
Investing in BAAA & BBBB before rate hikes can provide investors with competitive distributions and protection against an upward shift in the yield curve. During a Fed rate hiking cycle, as short-term interest rates rise, BAAA & BBBB can both offer investors stability and capital protection due to ultra-low duration, and the opportunity for increasing income due to their high-quality floating-rate CLO holdings.